COVERED RESEARCH
What our carrier and policy data shows about coverage gaps, carrier access, and the risk now sitting inside mortgage portfolios.
Drawn from Covered's footprint across our technology partners, spanning 10 million servicing loans and POS relationships that touch almost half of all US originations.
Published October 2026
PDF, 11 pages
Free, no form
A note from Covered's CTO
We didn't set out to write a market report. We set out to answer a question our lender
partners kept asking in different ways: how much of the insurance risk on our books can
we actually see?
Most of the time, a policy gets verified at closing and then goes quiet for years. Replacement costs climb, carriers stop writing in markets they used to serve,
and nothing in a servicing system flags either one. By the time anyone notices, the
homeowner is underinsured.
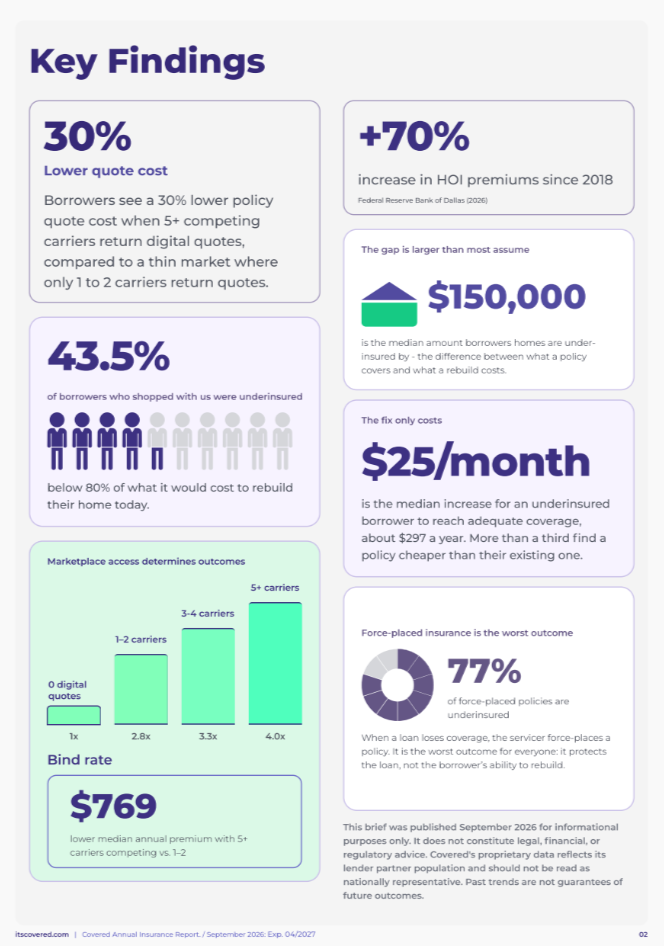
What we have that most people don't is the quote-and-bind data underneath that problem. We see what carriers actually return, what borrowers actually pay, and how far policy limits have drifted from what it would cost to rebuild. This report puts numbers on it and says plainly what we think it means for the next few years.

Chief Technology Officer, Covered Insurance Solutions
Four sections, built on two proprietary datasets
Third-party research is used to put our coverage data in context with market costs and loan performance.
Why homeowners insurance has outpaced every major cost category since 2019, and why rising rebuild costs are a big part of the reason.
How policy limits compare to replacement cost across our book, how far below the line
the gaps sit, and what it costs to close them.
What happens to a borrower's premium and their options when several carriers compete
versus one or two.
Why an underinsured or non-renewed policy shows up later as a servicing and delinquency
problem, and what lenders can do about it now.
Where the numbers come from
Proprietary Data
What it measures
Window
Dwelling limits against estimated replacement cost, by property.
January to August 2026.
Carrier appetite and quote availability, including markets where no carrier returns a digital quote.
January to August 2026.
Ge, Johnson & Tzur-Ilan, Federal Reserve Bank of Dallas, March 2026. Used for premium growth and the relationship between insurance cost and mortgage delinquency. U.S. Bureau of Labor Statistics, Consumer Price Index, for cost comparisons.
Cotality reconstruction cost research, May 2025.
First Street Foundation, 12th National Risk Assessment, 2025.
Financial Stability Oversight Council, 2024 Annual Report.
Full methodology, definitions, and per-figure citations are in the appendix of the PDF.
Covered's proprietary data reflects the borrower population of our lender partners and
should not be read as nationally representative.
Most lenders can tell you which policies lapsed. Very few can tell you which ones are intact and current but covering only a fraction of what the house would cost to rebuild.
Covered helps mortgage companies manage insurance health across a book of loans, so coverage gaps and
non-renewals surface while there's still time to act on them.

Hours of Operation
Monday to Friday
6 AM to 7 PM MT
Saturday
8 AM to 5 PM MT
Sunday
Closed
Call Us
833-487-2683


“Quotes are presented solely for your convenience. Savings may vary. Rates are subject to change based upon the specific coverage you select and other factors that apply to your situation. CA License #0M81402, doing business as Cubbard Insurance Solutions in California.”